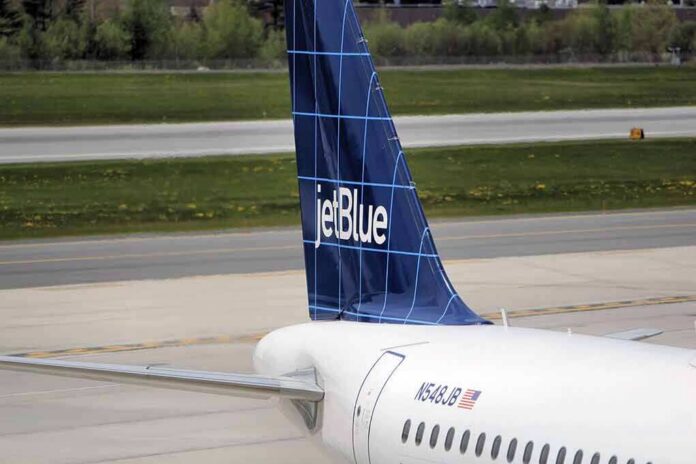
JetBlue says it can return to steady profit by 2027 even as some of its biggest lenders hire restructuring advisers to scrutinize billions in debt.
Story Highlights
- JetBlue targets sustained operating profit in 2027 and at least $1 earnings per share with positive free cash flow in 2028.
- Senior creditors hired restructuring advisers as bond prices fell and debt worries grew.
- Management points to “JetForward” savings and margin gains as proof the plan is working.
- The test is time: can cash improvements arrive before major debt deadlines hit?
JetBlue Sets a Clock on Its Turnaround
JetBlue told investors it expects “sustained operating profitability” in 2027 and at least $1 in earnings per share with positive free cash flow in 2028. Leaders tied that outlook to cost and revenue actions under its “JetForward” plan and to recent margin improvement guidance. The company framed the next year as a build period and said fuel and other pressures remain, but it still sees gains ahead. That forecast anchors the carrier’s case that a rebound is underway.
The airline’s chief executive also addressed fears about its balance sheet and debt. After a sharp selloff in JetBlue bonds, she said the company is not in talks with creditors and is not planning a debt restructuring. She argued operations and margins are moving the right way and that the airline can fund its plan. Her comments aimed to steady customers, workers, and investors who fear a drawn-out fight with lenders could hurt the brand and service.
Creditors Move to Protect Their Position
A group of senior creditors hired investment and legal advisers to review options tied to JetBlue’s capital structure. That step followed falling prices in some JetBlue debt, including notes backed by the loyalty program, which signaled doubt about repayment terms in a high-rate, high-fuel world. Hiring advisers does not mean a bankruptcy filing is near, but it shows lenders want leverage and clarity on collateral and maturities as the turnaround timeline stretches into 2027 and 2028.
This tension reflects a common airline story. Management focuses on unit costs, on-time performance, and fares. Creditors focus on cash, collateral, and the schedule of payments. The core question is simple and hard: can JetBlue make enough cash, fast enough, to cover near-term needs while waiting for savings and revenue actions to hit full stride. The carrier’s own targets set the bar, and the dates now frame how both sides will judge success or failure.
JetForward’s Early Scorecard and Why It Matters
JetBlue says its JetForward projects are improving earnings. Management cites measured savings and expects further margin expansion as revenue holds and non-fuel costs ease. On recent calls, leaders pointed to year-over-year operating margin improvement in the third quarter and guided to more gains in the fourth quarter. If that trend continues into 2027, it could bridge the gap to the free cash flow target in 2028. These markers are the proof points investors are watching now.
Turnarounds in airlines face forces they do not control. Fuel prices can jump. Planes can be late to deliver. Labor deals can raise costs. Demand can swing with the economy. These risks help explain why creditors want a backstop plan even as leaders claim progress. The airline’s job is to bank wins it can control—reliability, schedule discipline, and ancillary revenue—so that swings in fuel or demand do not break the plan’s math before 2027 arrives.
Why Regular Flyers Should Care
Customers want to know if tickets and loyalty points are safe. Today’s reporting does not show a filing or a restructuring plan. Management says flights will continue, and the company is pushing to improve service and margins. Creditors have taken steps to study their options. Those moves can exist at the same time. Travelers should watch official company notices and earnings updates for any change in schedule, policies, or loyalty program terms tied to financing decisions.
For many readers, this story hits a broader nerve. People see big firms borrow in good times and then struggle when costs rise. They feel leaders talk up plans while the bill comes due. JetBlue’s next year will test whether steady, basic execution can beat rising rates and higher fuel. If the airline hits its own milestones, it can prove that focus and discipline still matter more than hype. If it misses, lenders will likely push for faster, tougher fixes.
Sources:
theatlantic.com, aerotime.aero